Buying a House With Parents: Pros and Risks
Short answer
Buying a house with parents can help you qualify because a lender adds both incomes, but it also ties your parent to the full loan. There are four common paths: a gift, a non occupant co borrower, living together, or a parent who buys and rents to you. With FHA, a family co borrower on a one unit home still allows 3.5 percent down.
You are at your parents' dinner table, the same one you did homework on. Your father slides a printout across the wood. It is a listing you sent him last week. He has circled the price and written your name and his name side by side in the margin. "Together," he says. "Why not?" Buying a house with parents had never crossed your mind until this second.
Buying a house with parents can be the bridge that gets you across. Two incomes qualify for more than one. Family money and family credit can make a payment possible years earlier. But a bridge carries weight in both directions. When your name and your parents' names sit on the same loan and the same deed, every late payment, every disagreement and every life change crosses with you. Here is how to see the whole span before you step on it.
The four ways to buy with parents
What it means: when we say "buying with parents," we mean any setup where a parent's money, income or name helps you get the home. There are four common paths, and they carry very different risks.
| Path | What the parent does | On the loan? | On the title? | Risk to the parent |
|---|---|---|---|---|
| Gift | Gives money toward the down payment | No | No | Low: the money is gone, but nothing more is owed |
| Non occupant co borrower | Adds income and credit to qualify, does not live there | Yes | Yes | High: fully responsible for the whole loan |
| Live together | Buys with you and moves in | Yes | Yes | High, shared with you day to day |
| Parent buys, you rent | Parent owns the home, you pay rent | Parent only | Parent only | Medium: parent carries the loan and landlord duties |
| Term | What it means in plain words |
|---|---|
| Co borrower | A person who signs the loan and is legally responsible for every payment |
| Non occupant co borrower | A co borrower who will not live in the home |
| Title | Legal ownership of the property, recorded with the county |
| Debt to income ratio | Your monthly debt payments divided by your gross monthly income |
How FHA treats a parent who does not live there
FHA is friendly to families here. A parent can be a non occupant co borrower and you can still put down just 3.5 percent, as long as the parent is a family member and the home is a single unit.
A few rules come with it:
- At least one borrower must live in the home as a primary residence.
- The parent signs the loan and goes on title. They are an owner, not just a helper.
- The parent must live in the United States or be a U.S. citizen, and must qualify on their own credit and income.
- Many lenders use the lowest middle credit score among all borrowers, so adding a parent will not lift a weak score.
The worked example: why two incomes change everything
You want a $450,000 home with an FHA loan at 6.5 percent, 3.5 percent down. The full monthly payment, with taxes, insurance and mortgage insurance, comes to about $3,555.
You earn $6,000 a month before taxes and pay $500 a month on a car. Your father earns $7,000 a month, owns his home outright, and pays $300 a month on a credit card.
Lenders often look for total debts at or under about 43 percent of income, though FHA can go higher with strong factors.
- 1You alone: $500 plus $3,555 equals $4,055. Divide by $6,000. Your ratio is about 68 percent. Too high.
- 2Together: add the incomes, $6,000 plus $7,000 equals $13,000.
- 3Add all debts: $500 plus $300 plus $3,555 equals $4,355.
- 4Divide: $4,355 divided by $13,000 is about 33.5 percent. That falls under the common lender guide of about 43 percent.
That drop is the whole reason this path exists. It is also the risk. Your father's income is now holding up a $3,555 monthly promise that he does not live under.
The risks, said plainly
This is the part families skip at the dinner table. Read it together.
| Risk | What happens | Who it hits |
|---|---|---|
| A late payment | It shows on every borrower's credit report | You and your parent |
| Your parent wants a loan later | The full payment counts against their debt ratio | Your parent |
| Your parent retires or loses income | Nothing changes on the loan, the payment is still owed | Both, if you cannot cover it |
| A parent passes away | Their share of the home goes through their estate, maybe to siblings | You and your siblings |
| You disagree about selling | One owner can force the issue, sometimes in court | Everyone |
| You marry or divorce | A spouse may not be on title, and the parent still is | You, your spouse, your parent |
Free guide · 8 page printable PDF
The Koizen Home Buying Checklist
Every step from twelve months out to your first ninety days at home: seven phases of checkboxes, the documents lenders ask for, and a cash to close worksheet.
How you hold title matters
Title is how the county records who owns the home. The words on the deed decide what happens if someone dies or wants out. In most states there are two common ways for family to own together.
| Type | How it works | Good for |
|---|---|---|
| Joint tenancy | Equal shares; when one owner dies, the others get their share automatically | Simple setups where everyone agrees on who inherits |
| Tenants in common | Shares can be unequal, such as 80 and 20; each share passes by will or trust | Families who want the parent's share to go to siblings, or uneven contributions |
Rules differ by state, and California has its own community property and property tax rules. Talk to a real estate attorney before you sign the deed, not after.
Plan the exit before you go in
The best version of this story ends with your parent stepping off the loan. You do that by refinancing into your name alone once your income can carry the payment. Your loan balance falls slowly at first, then faster.
To refinance alone, you need your own debt ratio under the lender's limit. Using the example, your car payment plus the full house payment must fit inside about 43 percent of your income. That means a gross income near $9,400 a month, or about $113,000 a year, at today's numbers. A raise, a paid off car, or a lower rate later can bring that closer.
Set a review date each year. Look at your income, your rate, and your parent's needs. When the numbers work, release them.
Common mistakes
| Mistake | Why it hurts | Do this instead |
|---|---|---|
| Treating a co borrower as a cosigner on paper only | The parent owes the full loan and is an owner | Explain the full responsibility before anyone signs |
| No written agreement | Memories differ when money gets tight | Write down payments, shares and a buyout plan |
| Choosing title by default | The wrong form can send a share to the wrong person | Pick joint tenancy or tenants in common on purpose |
| Ignoring the parent's retirement | Their future loans and budget carry your payment | Talk about how long they can stay on the loan |
| No exit plan | Your parent may be tied to the loan for 30 years | Set a target income and date to refinance alone |
| Leaving siblings out of the talk | Inheritance surprises split families | Tell siblings the plan and the title choice |
Your next steps
- 1Sit down with your parents and read the risk table out loud, together.
- 2Pick the path that fits: gift, non occupant co borrower, living together, or parent buys.
- 3Ask an FHA lender to run the numbers with and without your parent on the loan.
- 4Meet a real estate attorney about title and a written co ownership agreement.
- 5Set a target income and a yearly review date for refinancing your parent off the loan.
The bridge holds when both ends are anchored.
Walk it slowly, together.
Then let them rest on their side.
Questions people ask
Can my parents be on my mortgage if they do not live in the house?
Yes. FHA allows a parent to be a non occupant co borrower, and with a family member on a one unit home the down payment can stay at 3.5 percent. The parent signs the loan, goes on title and must qualify on their own credit and income.
Does adding a parent to the mortgage help my credit score?
Usually not. Many lenders use the lowest middle credit score among all borrowers, so a parent's stronger score will not lift a weak one. What the parent's income can change is your debt to income ratio.
How much does a parent's income help me qualify?
In this guide's example, your ratio alone is about 68 percent, which is too high. Adding your father's $7,000 monthly income brings the combined ratio to about 33.5 percent, under the common lender guide of about 43 percent.
What are the risks for a parent on my mortgage?
To the lender, a co borrower owes every dollar of the loan, not half. A late payment shows on every borrower's credit report, and the full payment counts against the parent's debt ratio if they want a loan later.
How do I get my parent off the mortgage later?
The usual exit is refinancing into your name alone once your income can carry the payment. In the guide's example, that takes a gross income near $9,400 a month, or about $113,000 a year, at today's numbers.
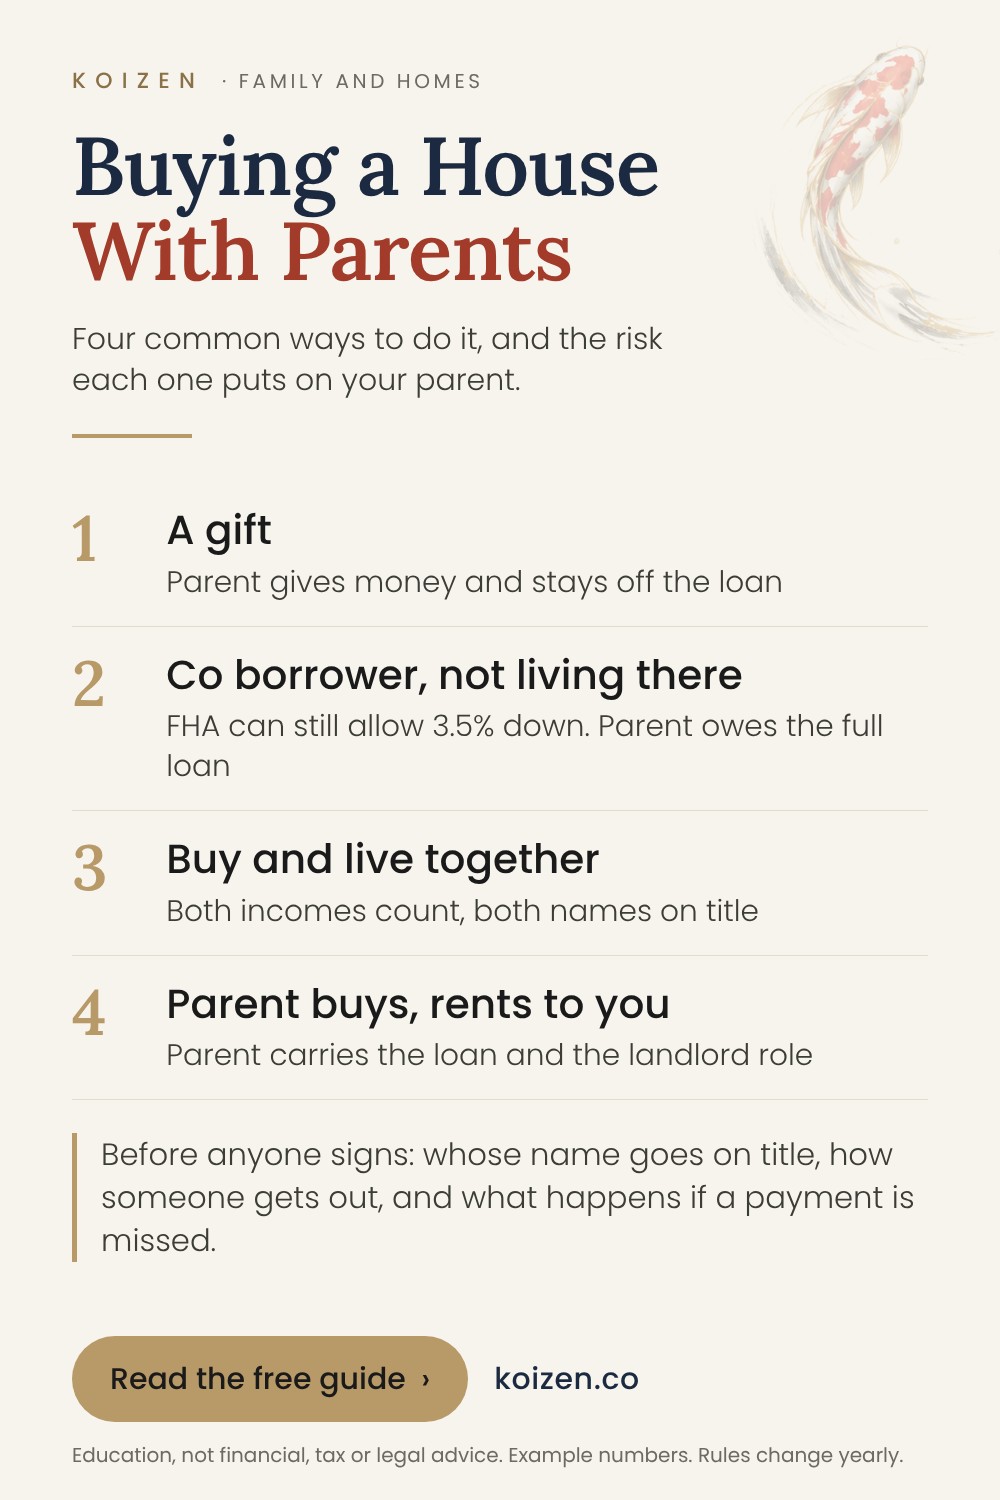
Save this guide for later
The key numbers on one page. Pin it to come back when you need it.
This guide is education, not financial, tax, legal or mortgage advice. Examples use made up numbers, and limits and rates change. Check the official sources linked above and talk with a qualified professional before you decide. Disclosures
Koizen is education, not financial, tax or legal advice. Rules and limits change; check the current figures with the agency or a licensed professional before you act. Some pages may contain affiliate links, always labeled, and they never change what we recommend.
Keep reading
FHA Gift Funds: Using Family Money for a Down Payment
Family wants to help with your down payment? FHA allows it, with rules. Who can give, the gift letter, the paper trail, and whether anyone owes tax.
CalHFA Down Payment Assistance Explained
MyHome, ZIP and Dream For All in plain words: who qualifies, how much cash it saves at closing, and what comes due when you sell or refinance.
FHA Loan in California 2026: Requirements, Limits and Costs
Low down payment, friendlier credit rules, and a mortgage insurance catch. The 2026 FHA limits by county and the full math on a $450,000 home.