FHA Loan Credit Score: What You Need to Qualify
Short answer
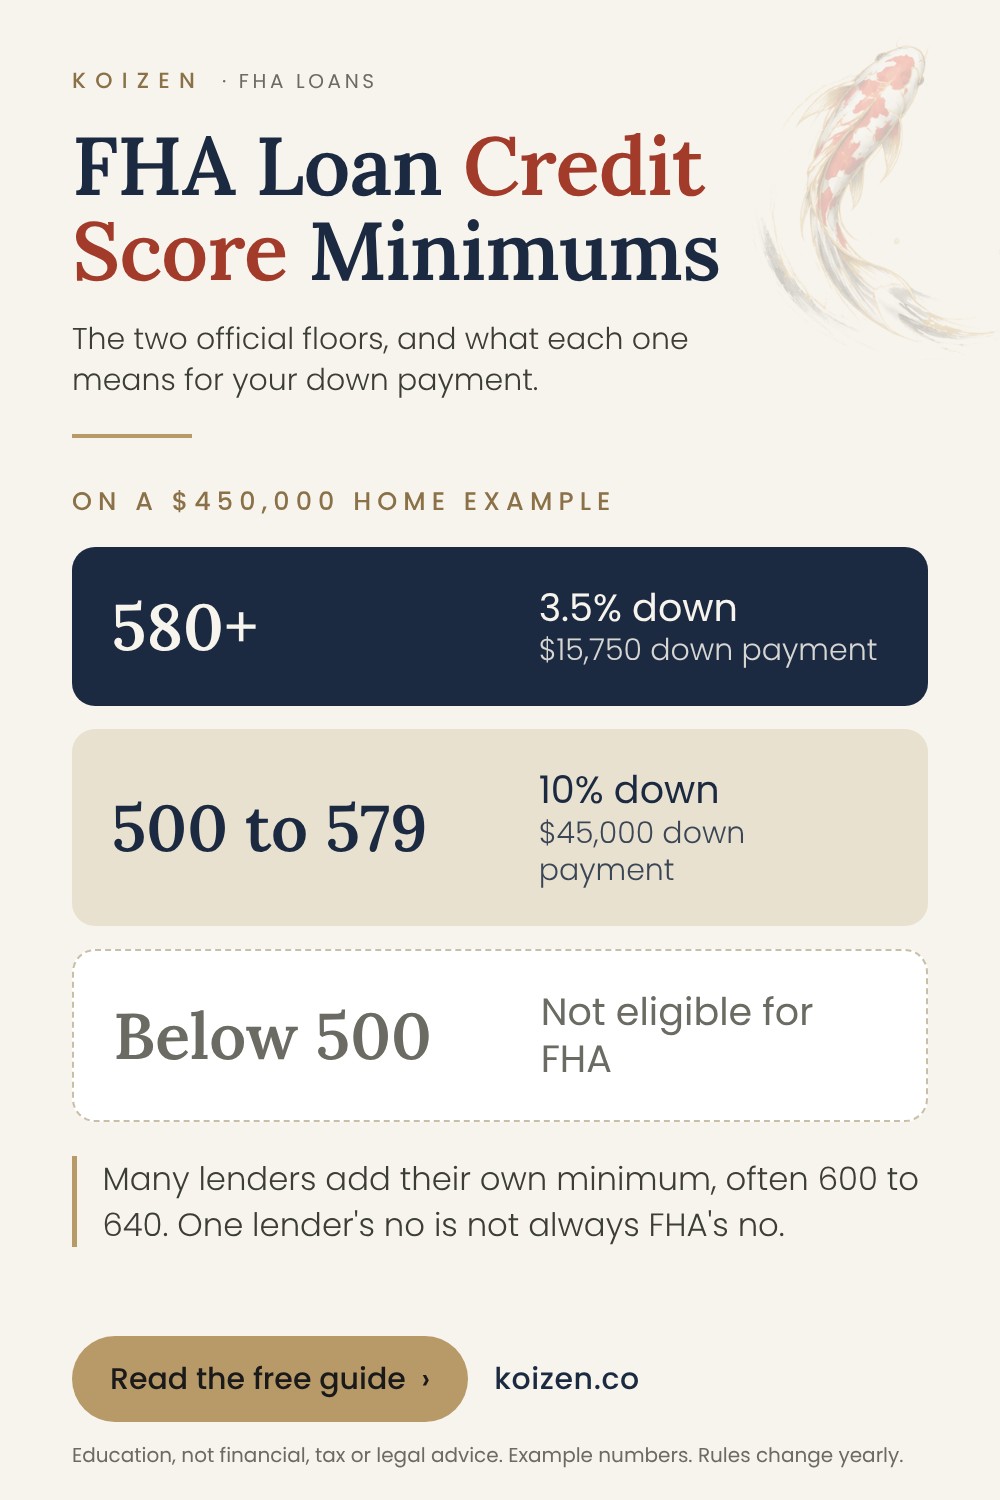
FHA sets two credit score floors. With a middle score of 580 or higher, you can put 3.5 percent down. With a score from 500 to 579, you need 10 percent down, and below 500 you are not eligible. Many lenders add their own overlays and want 600, 620 or even 640, so one lender's no is not always FHA's no.
You open the credit app on your phone while the coffee brews. There it is, a three digit number in a colored ring: 592. The ring is yellow, not green. You have heard people say you need a 700 to buy a house, and for a second the whole idea of owning a home slides a little further away. You type three words into the search bar: FHA loan credit score. What do you actually need?
Take a breath. The answer is gentler than you think. FHA was built for people who are still climbing. Picture your score as a ladder leaning against the front door. You do not need to reach the top rung. You need to reach the right rung, and know which rungs are worth climbing next. Here is the ladder, rung by rung.
What a credit score is, and which one the lender uses
What it means: a credit score is a number, usually from 300 to 850, that predicts how likely you are to pay a loan on time. It is built from your credit reports at the three bureaus: Equifax, Experian and TransUnion.
| Term | What it means in plain words |
|---|---|
| Credit report | The record of your loans, cards, payments and collections |
| Credit score | A number calculated from that report |
| Middle score | The lender pulls three scores, one per bureau, and uses the one in the middle |
| Lender overlay | An extra rule a lender adds on top of FHA's minimum |
| Utilization | How much of your credit card limits you are using, as a percent |
The score in your app is often not the one your lender sees. Mortgage lenders typically use older FICO versions built for home loans. Your mortgage score can be higher or lower than your app by 20 points or more. Ask a lender to pull it before you guess.
The FHA minimums
These are FHA's own floors. They decide how much you must put down.
That is the official ladder. In real life, most lenders add an overlay. Many want 600, 620 or even 640 before they will take an FHA application, because lower scores are more work and more risk for them.
| Score | FHA rule | What you will likely find |
|---|---|---|
| 640 and up | 3.5 percent down | Most FHA lenders will work with you |
| 620 to 639 | 3.5 percent down | Many lenders, a few may ask for more documents |
| 580 to 619 | 3.5 percent down | Fewer lenders; shop around, some specialize in this range |
| 500 to 579 | 10 percent down | Only a small number of lenders, often with manual review |
| Below 500 | Not eligible | Work on your credit first |
The worked example: what 20 points is worth
Let us follow one $450,000 home. Two buyers, same house, same income. One has a middle score of 582. The other has 568.
- 1Buyer with 582: 3.5 percent down. $450,000 times 0.035 equals $15,750.
- 2Buyer with 568: 10 percent down. $450,000 times 0.10 equals $45,000.
- 3The difference: $45,000 minus $15,750 equals $29,250.
Fourteen points. Almost $30,000 more in cash. That is why the 580 rung matters more than any other on the ladder.
The 10 percent buyer does get a smaller loan and, because of the larger down payment, may be able to drop FHA annual mortgage insurance after 11 years. But for most first time buyers, finding an extra $29,250 is much harder than raising a score by 14 points.
How your score affects the rate and payment
FHA mortgage insurance is the same price whatever your score. That is one of FHA's biggest gifts to people rebuilding credit. Conventional loans charge more for mortgage insurance when the score is lower. FHA does not.
Your interest rate can still move with your score, because lenders price their own risk. Here is how example rates might change the payment on a $441,850 loan, which is $450,000 minus 3.5 percent down, plus the upfront FHA insurance.
| Example score | Example rate | Principal and interest |
|---|---|---|
| 680 and up | 6.25 percent | $2,721 |
| 620 to 679 | 6.5 percent | $2,793 |
| 580 to 619 | 6.875 percent | $2,903 |
Rates change daily and differ by lender. These are examples only, so check current figures with two or three lenders on the same day.
Free guide · 7 page printable PDF
12 Things to Know Before Buying a House
The twelve lessons most first time buyers learn too late, each with a worked example in real numbers and one clear thing to do.
How to climb a rung in 60 to 90 days
Scores are not fixed. Some moves work quickly. Here are the ones that tend to matter most for a buyer near 580 or 620.
| Move | Why it works | How fast |
|---|---|---|
| Pay card balances below 30 percent of the limit, ideally below 10 | Utilization is a large part of the score | Next statement, about 30 days |
| Pay before the statement date, not the due date | The bureaus see the lower balance | Next statement |
| Dispute errors on your reports | Wrong late payments or accounts can be removed | 30 to 45 days |
| Never miss a payment from today on | Payment history is the largest factor | Builds every month |
| Do not open new cards or loans | New inquiries and accounts lower the score briefly | Avoids a drop |
| Ask your lender about a rapid rescore | The lender sends proof of paid balances to the bureaus | Often days |
Here is an example of how a score can move when utilization comes down. Every file is different, so treat this as an illustration.
If something serious is in your past
FHA allows you to come back after major credit events, with waiting periods. These are general guides, and lenders may add their own rules.
| Event | Typical FHA waiting period |
|---|---|
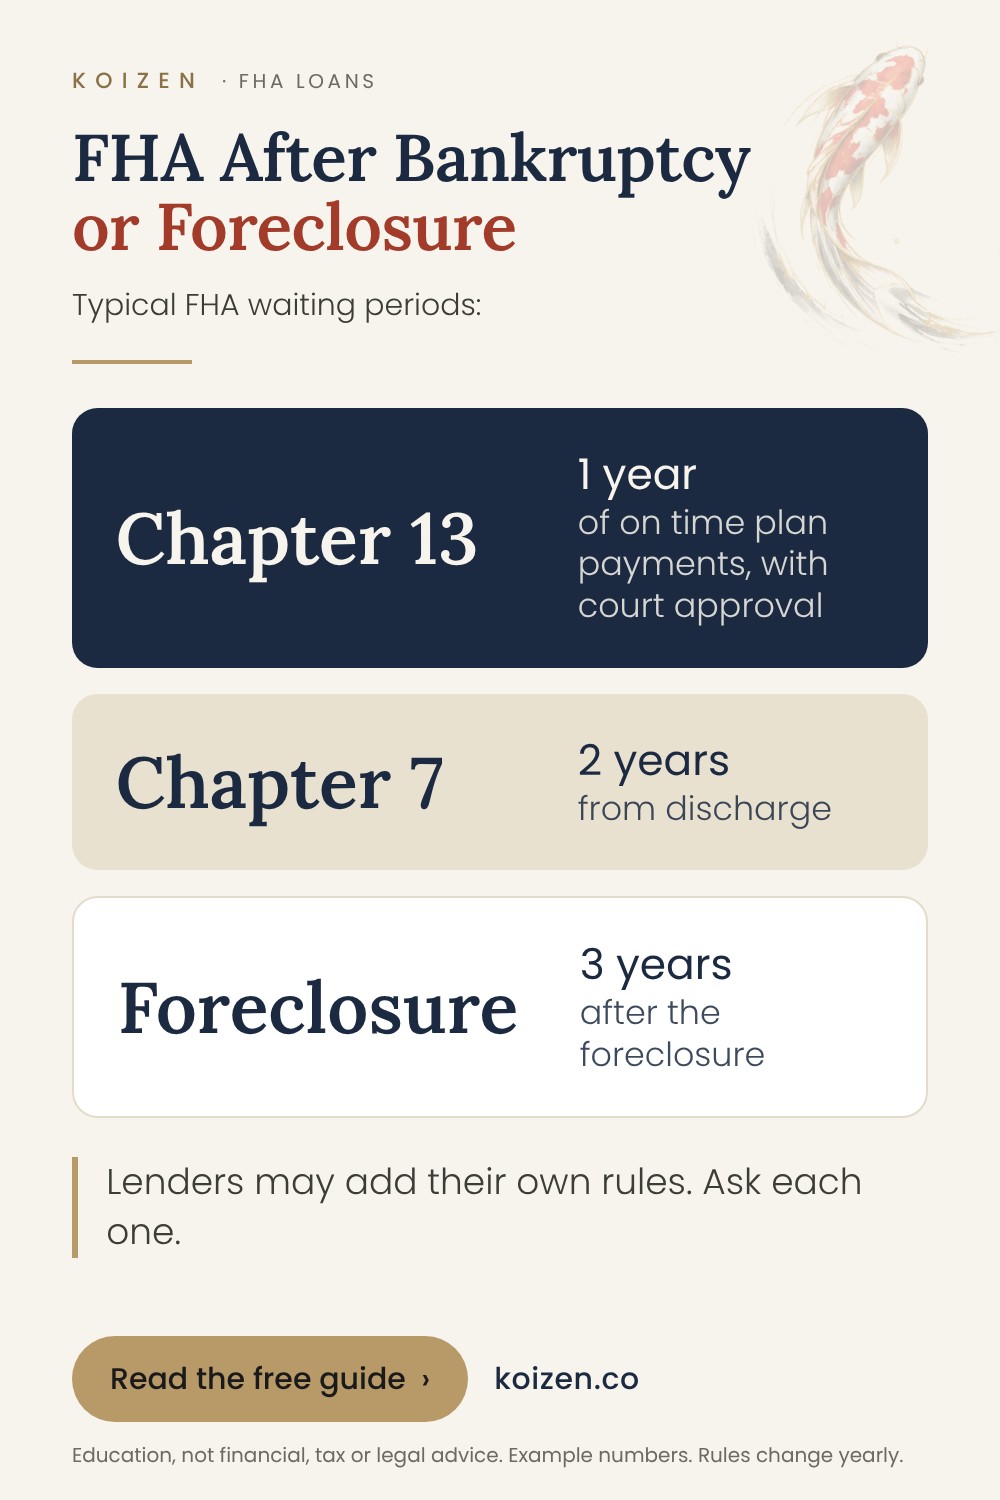
| Chapter 7 bankruptcy | 2 years from discharge |
| Chapter 13 bankruptcy | 1 year of on time plan payments, with court approval |
| Foreclosure | 3 years |
| Short sale or deed in lieu | Usually 3 years |
Lenders also look past the score at the story. A bankruptcy caused by a medical crisis or a job loss you recovered from is treated differently from years of missed payments. Write a short letter that explains what happened, when it ended, and how your payments have looked since. Keep it to the facts. Underwriters read these letters, and a clear one can tip a borderline file toward yes.
If you have no credit score at all, FHA lets some lenders use other records, such as rent, utilities and phone bills, through a manual review. Ask for a lender experienced with this.
Common mistakes
| Mistake | Why it hurts | Do this instead |
|---|---|---|
| Trusting the app score | The mortgage score may be lower or higher | Ask a lender to pull your mortgage scores |
| Giving up after one denial | It may be that lender's overlay | Ask about overlays, and try other lenders |
| Closing old cards | Your limits shrink, and utilization jumps | Keep old cards open and unused |
| Opening a new card for a store discount | A new inquiry can drop your score right before you apply | Wait until after closing |
| Paying down cards on the due date | The bureaus already saw the high balance | Pay before the statement date |
| Ignoring the 580 line | It can cost tens of thousands in extra down payment | Make reaching 580 the first goal |
Your next steps
- 1Pull your free reports from all three bureaus and dispute any errors.
- 2List every card with its balance and limit, and pay the highest utilization first.
- 3Ask one or two FHA lenders to pull your mortgage scores and tell you their minimums.
- 4If you are below 580, set a 90 day plan to cross it before you shop for homes.
- 5Once you qualify, compare rates from three lenders on the same day.
You do not need the top of the ladder.
You need the right rung.
Then the door opens.
Questions people ask
What is the minimum credit score for an FHA loan?
FHA's floor is 500. A middle score of 580 or higher qualifies for 3.5 percent down, a score from 500 to 579 requires 10 percent down, and a score below 500 is not eligible.
How much does reaching 580 change the down payment?
In this guide's example on a $450,000 home, 3.5 percent down is $15,750 while 10 percent down is $45,000, a difference of $29,250. If family is helping with that cash, see how FHA gift funds work.
Why would a lender deny an FHA loan when my score is above 580?
Many lenders add an overlay, an extra rule on top of FHA's minimum, and want 600, 620 or even 640. Ask each lender, "What is your minimum score for FHA?" and try another lender if needed.
Which credit score does an FHA lender use?
The lender pulls three scores, one per bureau, and uses the middle one. With a co borrower, many lenders use the lowest middle score of everyone on the loan, and your mortgage score can differ from your app score by 20 points or more.
How long after bankruptcy or foreclosure can you get an FHA loan?
Typical FHA waiting periods are 2 years from discharge for Chapter 7, 1 year of on time plan payments with court approval for Chapter 13, and 3 years after a foreclosure. Lenders may add their own rules.
Save this guide for later
The key numbers on one page. Pin it to come back when you need it.
This guide is education, not financial, tax, legal or mortgage advice. Examples use made up numbers, and limits and rates change. Check the official sources linked above and talk with a qualified professional before you decide. Disclosures
Koizen is education, not financial, tax or legal advice. Rules and limits change; check the current figures with the agency or a licensed professional before you act. Some pages may contain affiliate links, always labeled, and they never change what we recommend.
Keep reading
Buying a House With Parents: Pros and Risks
A parent on the loan can turn a no into a yes. Here are the four ways to buy together, the FHA rules, the real risks, and how to get your parent off later.
FHA Gift Funds: Using Family Money for a Down Payment
Family wants to help with your down payment? FHA allows it, with rules. Who can give, the gift letter, the paper trail, and whether anyone owes tax.
CalHFA Down Payment Assistance Explained
MyHome, ZIP and Dream For All in plain words: who qualifies, how much cash it saves at closing, and what comes due when you sell or refinance.